When Véronique thought no one would say yes again
Véronique wasn't the type of client who arrived feeling confident. At 39, as a mother of an 11-year-old boy, she worked as an administrative assistant at a private clinic on the North Shore, with a gross monthly income of about $4,200. On paper, it wasn’t catastrophic. But in real life, her file told a different story.
Two years earlier, after a difficult separation and several months of juggling credit cards, a personal line of credit, and late payments, she had to file a consumer proposal. Her credit score hovered around 548. Between rent, groceries, her son’s activities, and lingering old debts, she was living on a tight budget. She also had an old vehicle that was starting to cost more in repairs than it was actually worth.
What discouraged her the most wasn't just her financial situation. It was having already faced two rejections elsewhere. One dealer had even hinted, in no uncertain terms, that with her file, she should “lower her expectations.” That was the exact moment she lost hope.
When she filled out an application at Prêt Auto Québec, she did it late at night, almost without believing it would work.
A first call that changed the tone
The next morning, she received a call from our team. It wasn’t a rushed call, nor a scripted speech. It was just a real conversation. Véronique explained her consumer proposal, her recent rejections, and her fear of being judged once again. As she later said, for the first time, she didn’t feel like we were just looking at a credit score.
We talked to her about the Prêt Auto Québec 2nd chance program simply, without selling her a dream. We explained that a file like hers could be analyzed in its entirety: her stable income of over 3 years, her current job, her real budget, her ability to make a down payment, and the fact that she was actively regaining control of her finances.
The documents, the wait, and finally an answer
As with any real financing file, we asked her for a few specific documents: her last two pay stubs, a bank statement, her driver’s license, proof of address, and the documents related to her consumer proposal. Véronique feared this was a bad sign, but on the contrary, it was simply the normal step to building a solid file.
The analysis took a little less than 48 hours. During that wait, she said she felt anxious. She was afraid of a third rejection. She kept checking her phone constantly.
Then, the approval arrived.
Not a “miracle” approval, nor something unrealistic. A true 2nd chance approval, adapted to her situation.
Choosing the vehicle and a realistic solution
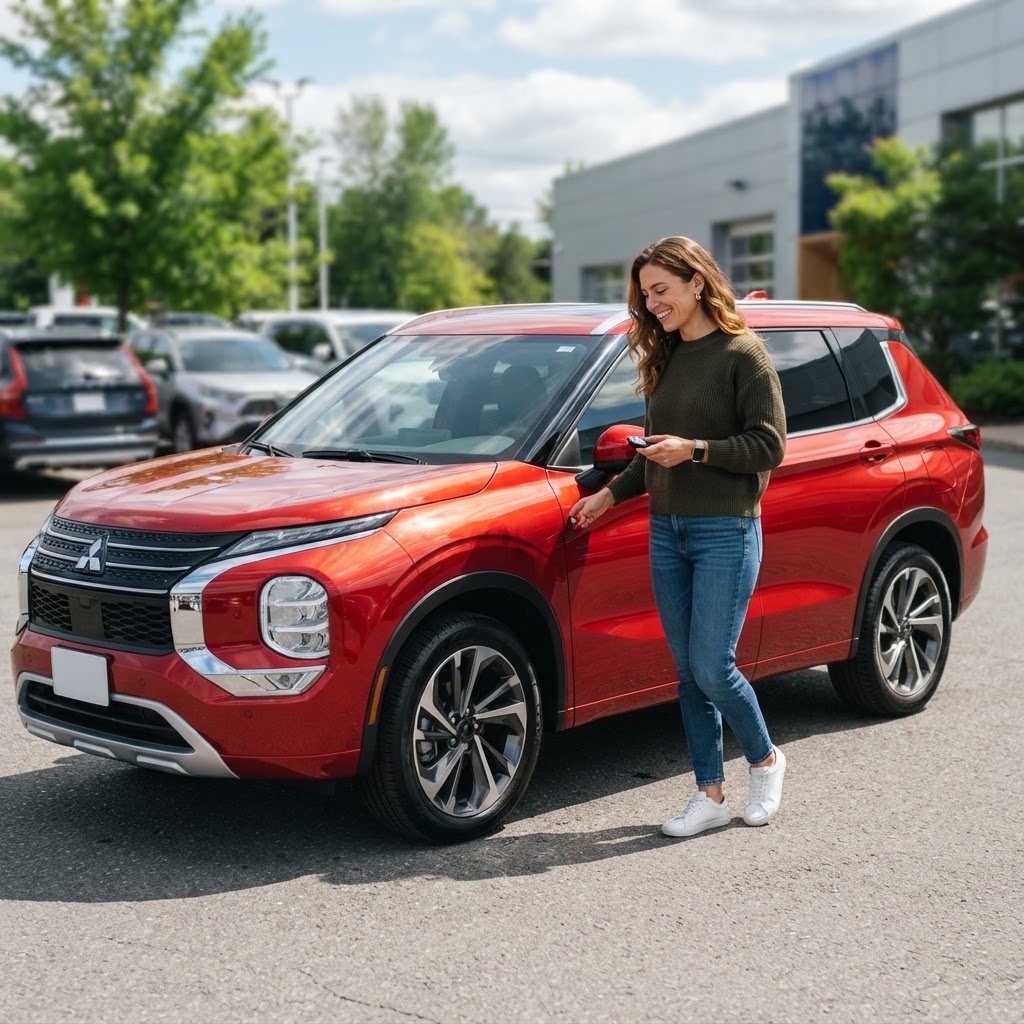
When we started talking about vehicles, Véronique wanted something reliable, modern, spacious enough for her daily life, but above all, a payment she could handle without stress. That’s when she settled on this 2026 Mitsubishi Outlander PHEV SE S-AWC.
She found it reassuring from the start: the driving position, the rear space, the all-wheel drive for winter, and the fact that it was a plug-in hybrid interested her, especially since she did many short trips during the week. She also said, laughing a little, that when she saw it in red, she finally felt like she was choosing something she truly liked, not just something “by default.”
In the end, her financing was approved with a $3,500 down payment, a rate of 12.49% over 84 months, for payments of about $689 per month. Was it a first-chance rate? No. Véronique knew that. But for her, what mattered was having an honest solution within the realistic parameters of a credit rebuilding file.
The signing moment
On the day of the signing, she arrived nervous. She had reviewed her numbers the night before, calculated her budget again, and prepared her questions. That’s often how it is with clients who have gone through a bankruptcy, a proposal, or rejections: they don’t want to be caught off guard again.
We went over the terms, the length of the loan, the payments, the importance of paying on time to rebuild her credit, and what this new loan could represent for her future. Not as a magic wand, but as a real stepping stone.
Véronique signed with slightly trembling hands. Then, when we handed her the keys, she had tears in her eyes. Not just because of the vehicle. Because of everything it represented. The fact that she had been heard. The fact that she had been approved despite her past. The fact that she was moving forward without shame.
Regaining confidence, one payment at a time
A few weeks after delivery, she gave us an update. She said she was sleeping better. She was no longer stressed every time her old vehicle made a strange noise. She also spoke of a deeper feeling: the sense of starting to trust herself financially again.
That’s what we often forget. 2nd chance financing isn't just about buying a vehicle. For many people, it is the first concrete step toward getting out of a period where everything seemed blocked.
Véronique didn’t have a perfect journey. She had a human journey. With mistakes, unexpected events, fatigue, and rejections. But she also had the courage to apply one more time.
If you recognize yourself in her story, know this: bad credit does not define your entire value. It describes a moment in life, not your whole story. If you want to see what is possible for you with our 2nd chance program, you can apply here: /demande.
Sometimes, rebuilding starts simply with someone finally taking the time to look further than just your credit file.