She thought it would be another rejection
Sandra could no longer get excited about the idea of changing vehicles. At 34, a mother of an 8-year-old boy, she had been working for a little over two years as an administrative assistant at a transport company in Lévis. Her income was around $52,000 per year, which was stable, but her credit file told a different story.
Three years earlier, after a difficult separation and several months of juggling rent, a maxed-out credit card, and a personal loan she could no longer keep up with, she had filed a consumer proposal. Added to that was an old late payment on her cell phone and two financing requests refused elsewhere in recent months. Her credit score had climbed back up a bit but remained around 568. Not catastrophic to the point of blocking everything, but low enough that every request became a source of anxiety.
When she started looking for a newer SUV, it was mainly out of necessity. Her old car was starting to cost too much in repairs, and winter was approaching. She wanted something reliable, with all-wheel drive, without falling into an impossible payment. The 2026 Mitsubishi Eclipse Cross SE S-AWC caught her attention right away. She found it spacious enough for the school-work-grocery routine, but not too big either. She still hesitated before applying.
She told me later that when she sent her request, she was already expecting to receive “the same polite ‘no’ as everywhere else.”
An imperfect file, but a solid situation
What we looked at with her
What changed in her case wasn't magic. It was the fact that we looked at the entire file, not just a credit score. Sandra had a stable job, her rent payments had been made correctly for over 18 months, her consumer proposal was being respected, and she hadn't accumulated any new unnecessary debts. She still had about $7,800 left to pay back on her proposal, but she was doing so seriously.
In the Prêt Auto Québec specialized credit program, that is often where the work is done: restoring the human context behind the credit bureau. We asked her for very concrete documents, nothing extraordinary: her last two proofs of income, a void cheque, proof of address, her driver's license, and the details of her consumer proposal. She was afraid it would be intrusive, but deep down, it actually reassured her. For once, someone was taking the time to put her file together correctly.
The moment she almost gave up
The evening she sent us her paperwork, she wrote me a very simple message: “If this doesn't go through, I'll just fix my old car one more time.” You could feel that she was protecting herself from one more disappointment.
The next day, we had already started presenting her file to our partners. There was some nervousness because her recent refusals were working against her. But her income, her job stability, and her down payment made a real difference. She had managed to set aside $2,500. It wasn't a huge amount, but it was enough to show her willingness to get back on a better path.
Approval in 48 hours
The approval came through less than 48 hours after her request. When we called her, she initially thought a document was missing. When she realized it was accepted, she cried. Not for long, not dramatically. Just that release you see in someone who has spent too much time being told no.
The financing chosen was realistic for her profile: a 72-month term at 11.99%. With her $2,500 down payment, taxes, and the chosen vehicle, her monthly payment came to about $412 every two weeks. It wasn't “perfect,” and we never sold it to her as a miracle. Instead, we explained frankly that the goal with 2nd chance credit was to get back into a good payment rhythm, stabilize her file, and eventually regain access to better conditions later.
She appreciated that talk. No exaggerated promises. No pressure. Just a realistic plan.
The day of signing
A simple but symbolic step
On the day of signing, Sandra was visibly stressed. Even though everything was approved, she still had that fear that something would block at the last minute. We calmly went over the numbers with her, reread the terms, and ensured she understood her commitment. It was important to us that she left feeling confident, not just relieved.
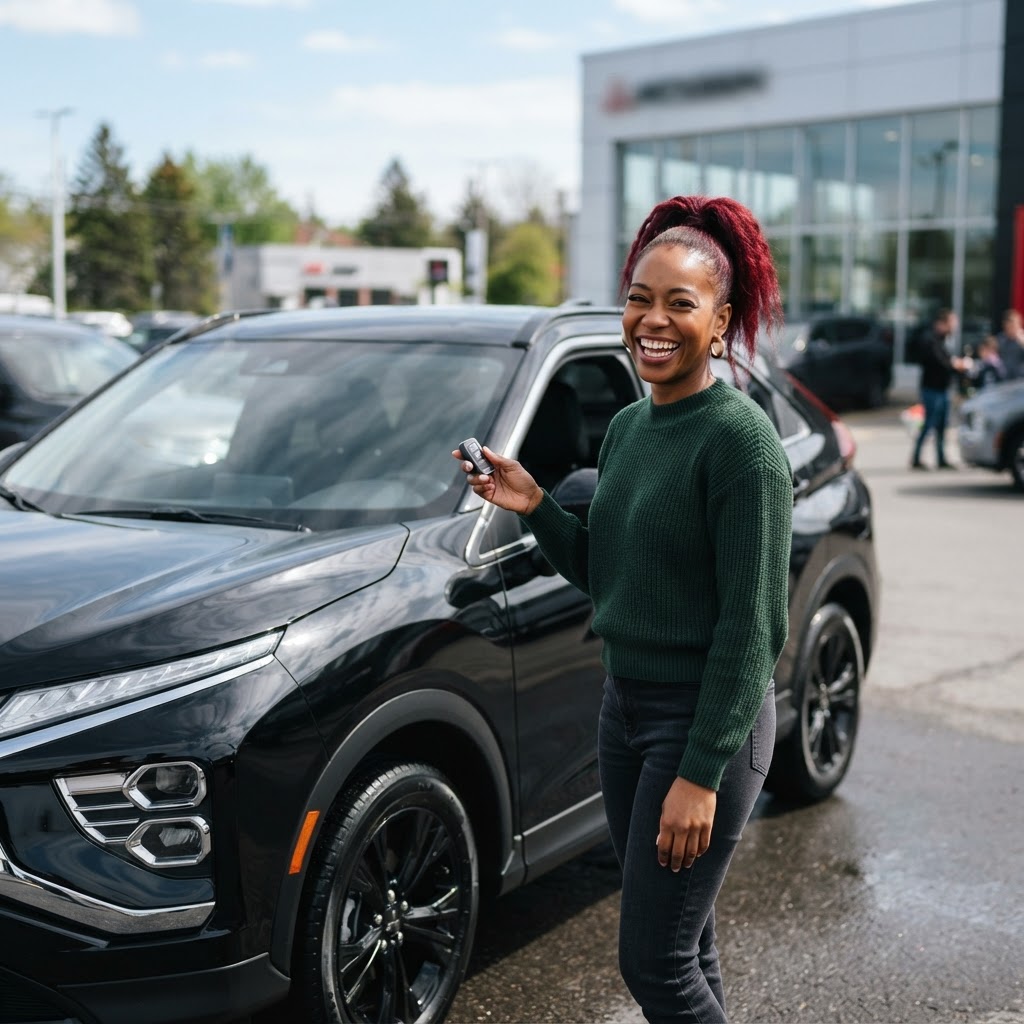
When she saw the black Mitsubishi Eclipse Cross SE S-AWC prepared for delivery, she had a big smile that she was almost trying to hide. She wasn't the expressive type, but it was clear she was already seeing herself starting over differently. Not like someone “who got lucky,” but like someone who was starting to trust herself again.
The handover of the keys was a beautiful moment. She called her sister from the parking lot, just before leaving. She said to her: “I think this is it. I am actually getting back on track.”
Today, she talks mostly about pride
A few months later, what Sandra remembers most isn't even the vehicle. It's the feeling of finally having broken the cycle of refusal and shame. She makes her payments on time, she monitors her credit, and she knows that this financing is part of her reconstruction.
Her story doesn't say that everything becomes easy all of a sudden. It says something else, more true: even with a consumer proposal, recent refusals, or a damaged score, there can still be a door open when the file is put together intelligently and humanely.
If you recognize yourself in this, don't condemn yourself before even starting the process. Make a request at /demande. We will look at your situation as it is, with respect, without judgment. And if Sandra's story can leave a message, it is this one: a bad financial chapter does not define you forever. Sometimes you need someone to help you turn the page, one approval at a time.