She thought it would be another 'no'
When Nathalie filled out her application at Prêt Auto Québec, she barely believed it would happen.
At 38, as a single mother to an 11-year-old son, she had been working for just over two years as an administrative assistant at a small business on the South Shore. Her gross income was around $4,200 per month, which allowed her to breathe a little easier than before, but her credit file told a different story. Two years earlier, following a difficult separation and several months of juggling minimum payments, she had been forced into a consumer proposal. Before that, there were late payments on two credit cards, a defaulted personal loan, and a vehicle repossession a few years prior.
Her score had climbed slowly but remained low, hovering around 565. Every time she reached out for financing, she felt like she was reliving the same scene: they would ask for her details, seem confident at first... then call her back to say it wouldn't be possible, or that she would need a co-signer she didn't have.
This time, she was eyeing a specific vehicle, the 2026 Mitsubishi Outlander PHEV SE S-AWC. Not for the luxury, nor to treat herself at any cost. She did a lot of driving between home, school, work, and visits to her mother in Boucherville, and she wanted something reliable, spacious, and, above all, easier on gas. She had been watching this model for a while, without daring to think it would be accessible to her.
The moment she almost gave up
The day before applying, Nathalie had received another rejection elsewhere. Not a brutal refusal, but the kind of answer that still stings: “Your file is a bit too fragile at the moment.” She told me she had closed her phone and sat at the kitchen table thinking she would be stuck with the bus, catching rides, and the stress of always relying on someone else whenever her son had an activity or appointment.
What she dreaded most wasn't just being told no. It was feeling judged.
A simple, yet human approach
When her file arrived at Prêt Auto Québec, we spoke to her frankly about our 2nd chance program. Not as a magic trick, but as a real solution for people who have had a financial setback and are ready for a fresh start.
We asked for standard documents for this type of financing: her last two pay stubs, a few bank statements, her driver’s license, proof of address, and the paperwork related to her ongoing and respected consumer proposal. Since she was stable in her employment and had been making her payments for several months without delay, her file was viable despite her history.
She told me that what calmed her down was that we never sold her a dream. We explained that with a credit score around 565 and her history, she should expect a 2nd chance rate higher than regular financing. We worked on her file accordingly, without beating around the bush.
The 24 to 48-hour wait that felt endless
The approval arrived about 36 hours later.
When we called her, Nathalie instinctively expected bad news. Instead, we confirmed she was approved with a $3,500 down payment, an 84-month term, and an 11.99% rate. Her monthly payment came out to about $823 for the 2026 Mitsubishi Outlander PHEV SE S-AWC, taking into account the authorized financing structure for her file.
Was it a small payment? No. And that is exactly why the conversation was important. We took the time to verify with her whether this amount truly fit into her budget, after accounting for her rent, insurance, groceries, and consumer proposal. She had some savings, a tax refund set aside, and help from her father to complete the down payment. That combination made the project realistic.
The day everything became real
When Nathalie came in to sign, she still had that guarded look you often see in clients who have been turned down multiple times. She reread everything. She asked questions about the rate, the possibility of rebuilding her credit, and the impact of making payments on time for 12 to 18 months.
And she was right to ask those questions.
We explained that the most important thing now was consistency. A vehicle financed through a 2nd chance program can become a real stepping stone if the payments are managed well. Not a miracle cure, but a solid step forward.
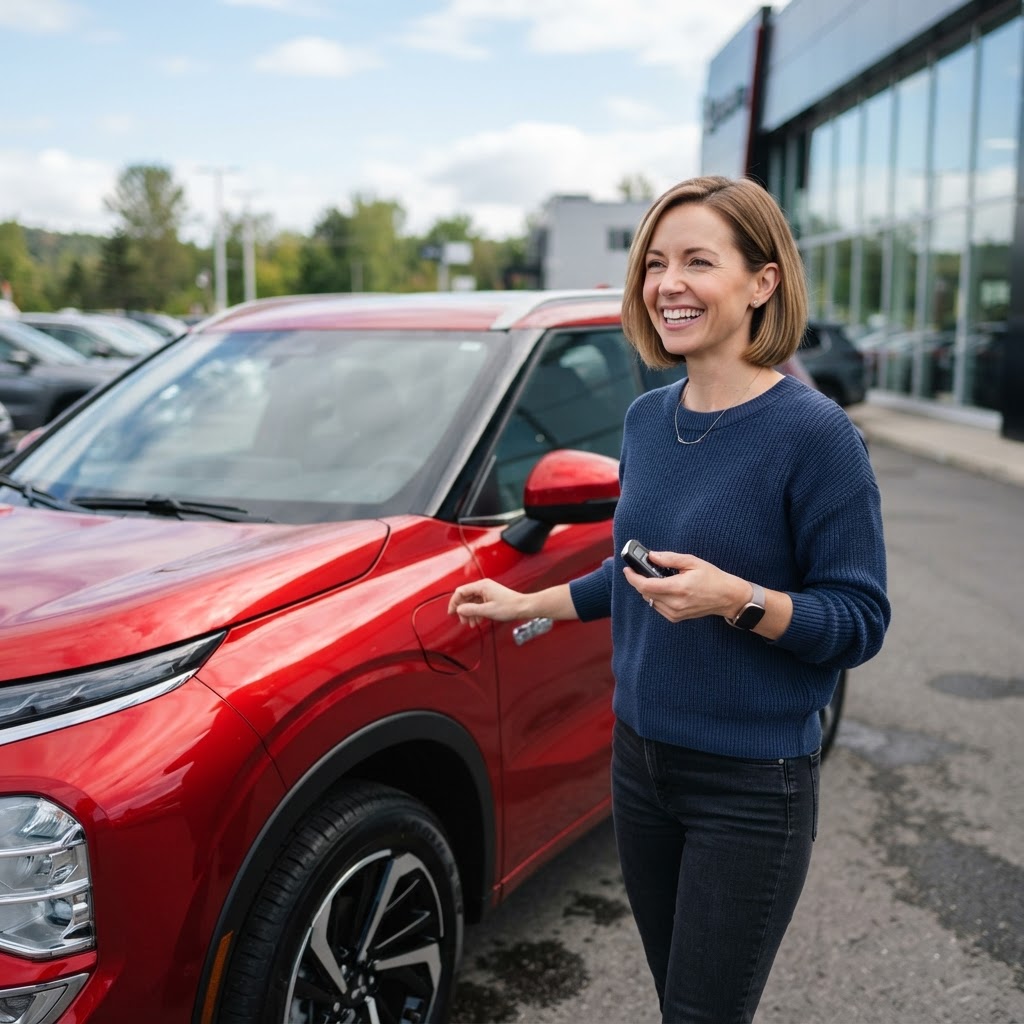
When she finally saw her red Outlander PHEV SE S-AWC ready for delivery, she had tears in her eyes. Not because of the vehicle itself, even though it was beautiful. But because of what it represented: she was no longer stuck in the mistakes of her past.
More than a car, a fresh start
A few weeks after delivery, Nathalie got in touch. She said she was sleeping better. That she didn’t spend her evenings calculating how to organize all her commutes. That she felt, for the first time in a long time, “back in her own life.”
What I remember about her is that quiet pride. She didn’t pretend that everything was solved. She knew that rebuilding credit takes time. But she had started moving forward again.
If you recognize yourself in her story — a bankruptcy, a consumer proposal, rejections, a score that follows you like a label — know that there are still doors open. The Prêt Auto Québec 2nd chance program is here to look at your situation as a whole, with realism and respect.
If you want to check your options, you can submit an application here: /demande.
And if right now you are ashamed of your file or afraid to try again, I would like to tell you this simply: a bad financial chapter does not define your whole story. Nathalie is proof of that. Sometimes, all it takes is an honest, well-managed yes to start believing in what comes next.