He thought no one would ever say yes again
When Jean-Philippe filled out his application, he didn't expect much. At 36, he was emerging from a period he describes as the most humiliating of his life. Two years earlier, after a difficult separation and several months off work, he had been forced to file a consumer proposal. Before that, he had accumulated too many late payments: maxed-out credit cards, an overdue personal loan, and several accounts sent to collections. His credit score was hovering around 518.
Yet, he was working full-time in a stable position as a warehouse clerk on the North Shore, with an annual income of about $49,000. But despite his income, every auto financing application he submitted ended with the same result: a rejection, or terms so harsh that he would close the page before even finishing. Once, he was asked for an $8,000 down payment. Another time, he was told to provide a co-signer. He had neither.
What truly broke him was when his old car finally started falling apart. A temperamental transmission, the check engine light flashing every other week, and endless repair bills. He needed a reliable vehicle for work, but he felt stuck in a vicious cycle: no credit, no car; no reliable car, higher risk of losing his job.
The moment he dared to apply again
Jean-Philippe later told us that it was the tone of the conversation that convinced him to see it through. He wasn't looking to be sold a car; he was looking for someone who understood what a fragile credit file means in the real world. When we spoke with him at Prêt Auto Québec, we talked openly about our specialized credit program without making him believe in miracles. We explained that a file like his could sometimes qualify for 4th chance credit, especially with a recent consumer proposal and several prior rejections elsewhere.
What he needed to hear was simple: no, his file wasn't perfect, but no, he wasn't "finished" either.
A properly prepared file
We asked him for the usual documents—nothing unusual: his last two pay stubs, a few bank statements, his driver’s license, proof of address, and the details of his consumer proposal. Since he received his pay via direct deposit and had been at the same job for over 18 months, it already helped paint a more stable picture for the lender.
The process was quite fast. It took about 24 to 48 hours to assemble the file, validate the documents, and come back with a realistic approval. During that time, Jean-Philippe confessed that he was checking his phone as if his life depended on it. He was still expecting another "no."
A realistic approval, not perfect—but possible
When the approval came through, he asked us to repeat the numbers. He had been approved for a 2027 Nissan Sentra S, a model that met exactly what he was looking for: something recent, fuel-efficient, reasonable to insure, and reliable enough to get him back on his feet. The vehicle listing was here: 2027 Nissan Sentra SENTRA S.
The financing was approved over 84 months at a rate of 12.99%. It’s not a prime rate, obviously, but for a client with a score around 518, a consumer proposal, and recent rejections, it was a real way out. He put $2,500 down, which he had managed to save by cutting back on everything for several months. His bi-weekly payment came to about $392, taxes included.
He hesitated before saying yes. Not because he didn't like the car, but because he was afraid of making another mistake. He asked a lot of questions, and honestly, that was a good thing. He wanted to understand the total cost, the terms, and what on-time payments could do for his credit file in 12 to 18 months. We took the time with him. Not to pressure him, but to ensure he left with a solution he could actually afford.
The day of signing, and keys in hand
Jean-Philippe still remembers the moment he came in to sign. He was nervous until the very last minute, as if someone was going to tell him it wouldn't work out after all. He read the documents twice. Then he signed.
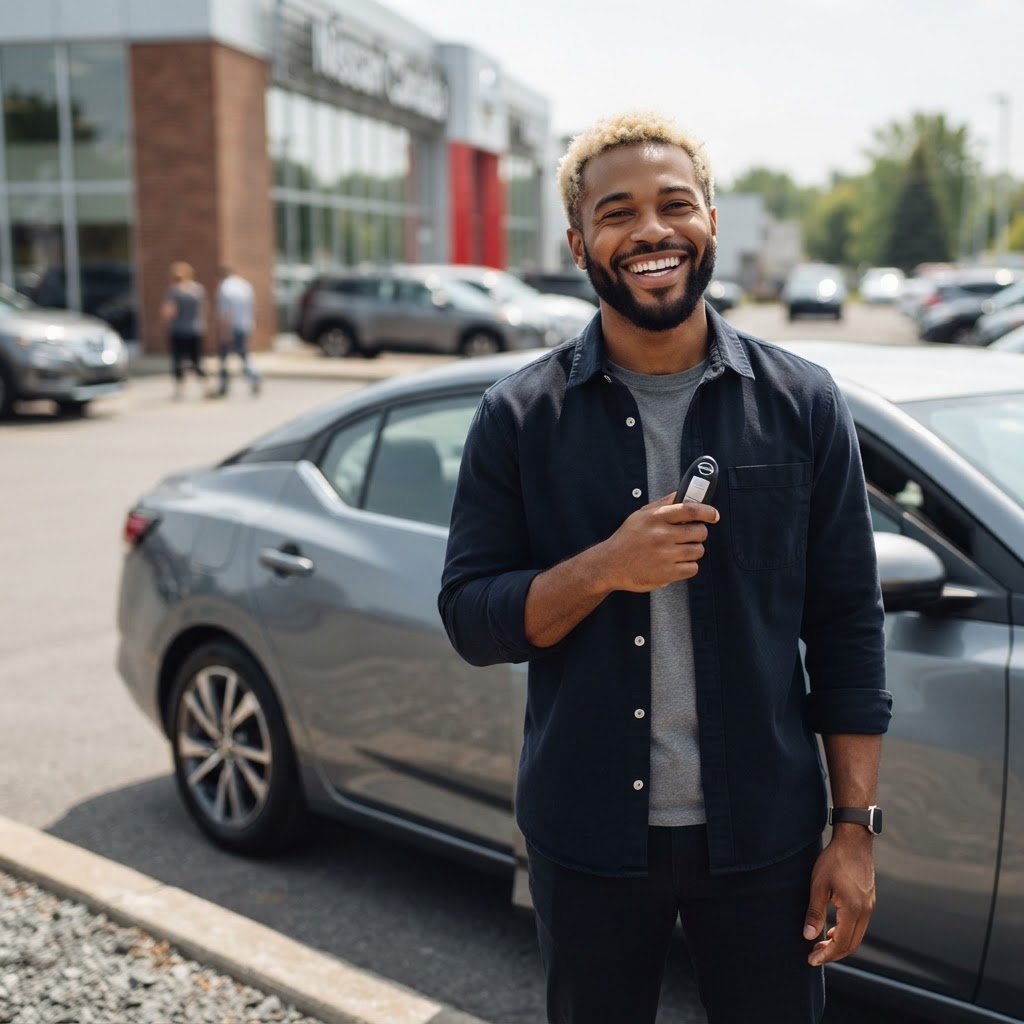
Handing over the keys was simple, yet very powerful. The gray Sentra was waiting for him, clean and ready to go. He didn't give a big speech. He just let out a long breath and smiled. A real smile of relief. It wasn't just a car. It was the feeling of finally breaking out of several years where everything felt locked down.
Rebuilding, one payment at a time
Months later, Jean-Philippe reached out with an update. He was making all his payments on time. He said he was sleeping better. He felt less judged and less trapped. Most of all, he had started believing again that he could rebuild his credit instead of just surviving with it.
That is probably the most important part of his story. The financing didn't erase his past. It didn't fix everything overnight. But it gave him a concrete tool to move forward, with a reliable vehicle and a realistic plan.
If your situation is a bit like his—bankruptcy, consumer proposal, rejections elsewhere, or badly damaged credit—don't write yourself off before speaking to someone who really understands these types of files. At Prêt Auto Québec, we often see people arrive feeling discouraged, only to leave with a solution tailored to their reality, without false promises.
You can take the first step here: /demande
And if you are reading this thinking it is too late for you, at least remember this: Jean-Philippe thought the same thing. Sometimes, rebuilding simply starts with an honest application, good guidance, and the courage to try one last time.