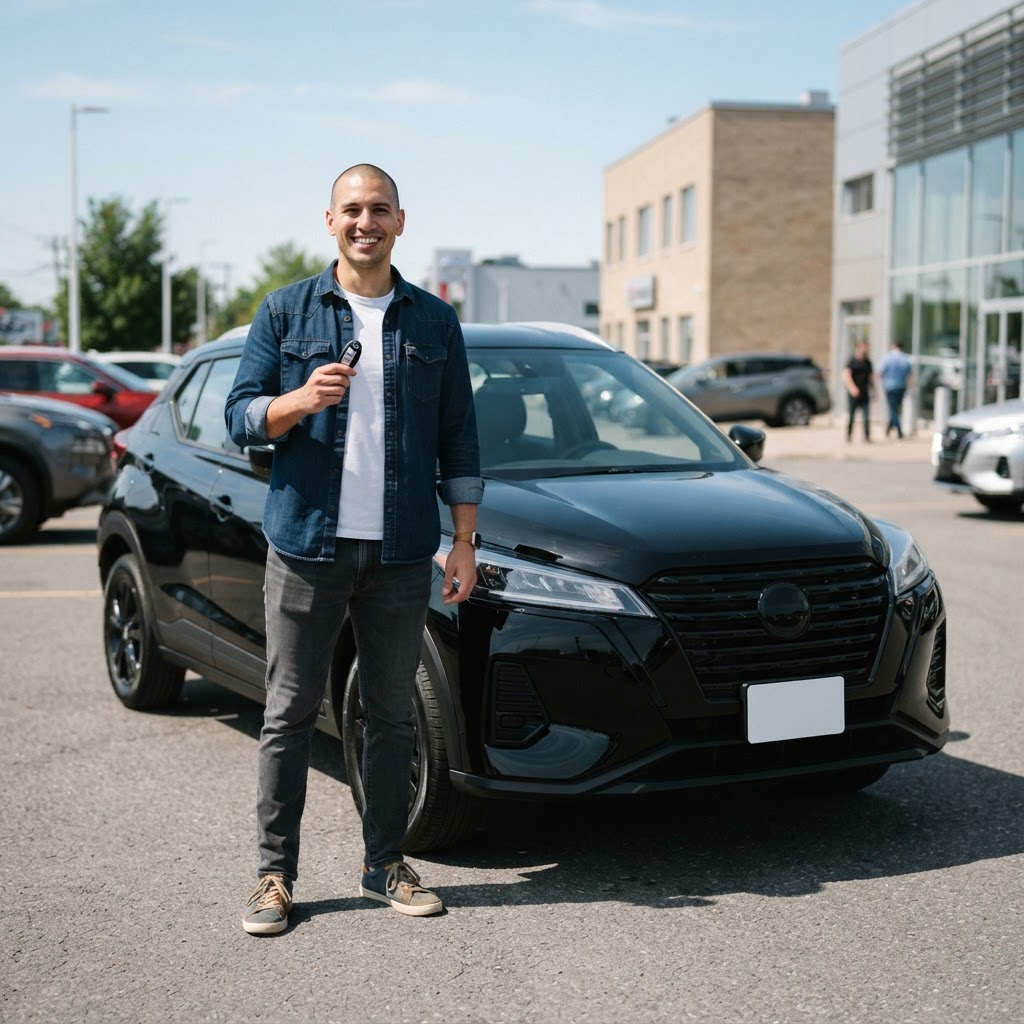
When Frédéric thought no one would say yes anymore Frédéric wasn’t the type to ask for help easily. At 39, he worked full-time in industrial maintenance on Montreal’s South Shore, earning about $4,200 gross per month. On paper, things didn’t look disastrous, but his credit file told a different story: a personal bankruptcy filed just over a year ago, about $38,000 in accumulated debt across credit cards, a line of credit, a personal loan, and several missed payments that had finally become overwhelming. His credit score hovered around 528 when he started looking for a vehicle. The hardest part wasn’t the numbers—it was the shame. He had already been turned down twice elsewhere. One dealer had rushed him without really listening; another had almost made him feel like his file wasn’t worth their time. After that, Frédéric convinced himself he’d be stuck with his old compact car for a long time, despite the mounting repair bills. Then, his car gave out on him one too many times on a Monday morning in his work parking lot. That day, he truly lost hope. ### A simple, non-judgmental first conversation When Frédéric reached out to Prêt Auto Québec, what he noticed immediately was that he wasn’t treated like a “bad credit file.” He was treated like someone trying to get back on their feet. We calmly explained that there are specialized credit programs for situations like his, and that in his case, the most relevant path was to look into car loans after bankruptcy. No empty promises, no “we guarantee everything,” just an honest discussion about his income, his budget, and what he could afford without getting back into trouble. Frédéric wanted something recent, reliable, and economical, but he was afraid to aim too high. When he saw the 2025 Nissan Kicks Play S FWD - ONE OWNER, NEVER ACCIDENTED, he allowed himself a glimmer of hope. He found the vehicle modern enough to restore his confidence without being excessive. ## Building a file when starting from behind The process was simpler than he imagined, even though he did have to provide documentation. We asked for his last two pay stubs, recent bank statements, proof of address, his driver’s license, and his bankruptcy discharge papers. Nothing unreasonable, just what was needed to present a clean file to specialized lenders. Frédéric was nervous while sending everything in. He feared one detail might cause another rejection. He remembered the feeling of being turned down without explanation. This time, however, the team stayed in contact. We called to tell him that his file was processing, that it was normal for certain checks to take time, and that answers typically came within 24 to 48 hours. As he said later: the wait felt endless. Not because it was long, but because he was putting more than just a purchase on the line. He was putting his dignity on the line. ### The approval that changed everything The call came late the following afternoon. Frédéric was almost expecting more bad news. Instead, he was told his approval had been secured. The financing terms were realistic: a $2,500 down payment, a 72-month term, at an interest rate of 12.49%. His payment came out to around $189 bi-weekly, including taxes and basic protections based on his file structure. It wasn’t “perfect” by prime rate standards, and no one tried to make him believe otherwise. But for someone coming out of bankruptcy who had been refused elsewhere, it was a concrete, viable solution tailored to his ability to pay. Frédéric took an evening to think it over. He crunched the numbers, checked his budget, and spoke with his sister. The next day, he called back. His voice was shaking a little, but he was ready. ## The day of signing The day he came to sign, he was tense. Not just because of the contract, but because of everything that moment represented. We went over every line with him: the amount financed, the rate, the term, and the payment terms. No pressure, no jargon thrown around too quickly. When he finally saw the Nissan Kicks in person—black, clean, and impeccable—there was a long silence. It’s often in those moments that you realize it’s not just a vehicle. It’s a fresh start. The handing over of the keys was simple, almost intimate. Frédéric had that mix of relief and pride rarely seen in an “ordinary” purchase. He hadn’t won the lottery; he had simply proven that after hitting rock bottom, he could start building something solid again. ### Regaining confidence, one payment at a time A few weeks later, he gave us an update. What he loved most, at the end of the day, wasn’t just driving a newer car. It was knowing that every on-time payment was helping him rebuild his credit. Slowly, yes. But surely. That’s something people often forget to say: specialized financing isn’t magic. It’s not an eraser for the past. It’s a tool that, when well-structured, helps you get moving in the right direction. For those who see themselves in Frédéric’s story, there might not be a perfect solution, but there can be an honest one. If your credit is closing doors for you right now, at least have your options checked. You can fill out an application here: /demande. And honestly, if you are in a period where you feel your file defines you, remember this: Frédéric thought the same thing. Today, he drives a reliable vehicle, sticks to his budget, and is rebuilding his credibility one payment at a time. Sometimes, starting over is already a great victory.
Find your ideal vehicle
Browse our vehicle inventory and use our free loan calculator.