When Sandra stopped believing she would ever get a 'Yes'
Sandra never thought she’d be sharing this story with a smile. At 36, a mother to a 9-year-old boy, she had been working for over two years as an assistant in a private clinic in Laval, with an annual income of around $46,000. On paper, it wasn’t a disaster. But in reality, her file still carried the scars of a few very difficult years.
Two years earlier, after a complicated separation and months spent juggling maxed-out credit cards, a late personal loan, and car payments that became impossible to manage, she had filed a consumer proposal. Her credit score had dropped to around 538. She had managed to catch her breath, yes, but every time she applied for financing, the answer was cold and swift: declined.
The most discouraging part was that she didn’t need a “luxury” vehicle. She simply wanted something reliable, recent, fuel-efficient, and practical enough to handle groceries, school runs, and the commute to work without the constant fear of a breakdown. When she saw the 2027 Nissan Kicks KICKS SR PRIVILÈGE, she thought it was the perfect fit for her life. Then, she almost immediately answered herself: “It’s no use dreaming, they’re going to turn me down again.”
The moment she almost gave up
Before speaking with Prêt Auto Québec, Sandra had tried elsewhere. One dealership asked for an impossibly high down payment—nearly $8,000—while making her feel like her file was “complicated.” Another never called her back. Eventually, she started to feel ashamed.
When she filled out an application at Prêt Auto Québec, she did it late at night, almost in secret, without much hope. She told herself she just wanted “the honest truth.” The next morning, a consultant called her with a tone that immediately put her at ease, but in a good way: no judgment, no pressure, just simple questions to understand her situation.
The consultant spoke about the 2nd chance program at Prêt Auto Québec as a real possibility, not just a slogan. She told her frankly that her file wasn't perfect, but it wasn't a dead end either. With her stable job, her history of consistent proposal payments, and a small down payment, there was something they could work with.
A file built with patience, step by step
Sandra had to provide the usual documents: her last two pay stubs, recent bank statements, her driver’s license, proof of address, and documentation regarding her consumer proposal. She feared this was the beginning of more complications. In the end, it was much simpler than she imagined.
In about 24 to 48 hours, the file was analyzed. What she appreciated was that she was explained every step. No endless silence, no vague messages. They told her where things stood, what the lender wanted to confirm, and most importantly, why.
The approval came with realistic conditions. For the Nissan Kicks, she was offered 2nd chance financing over 72 months with a $3,500 down payment. Her interest rate was 12.99%, which was higher than a prime rate, of course, but far from the catastrophic scenarios she had imagined. Her payment was around $268 bi-weekly, including taxes and basic protections based on her file structure. For Sandra, that was the key figure: could she live with this payment without struggling again? For the first time in a long time, the answer was yes.
The day it all became real
She still remembers the day she went to sign. She was nervous until the last minute, convinced that a single detail would derail everything. The consultant took the time to review the numbers with her calmly, without rushing or using unnecessary jargon. Sandra wanted to understand her commitment, the term, the cost of credit, and most importantly, how to use this financing as a stepping stone to rebuild her file.
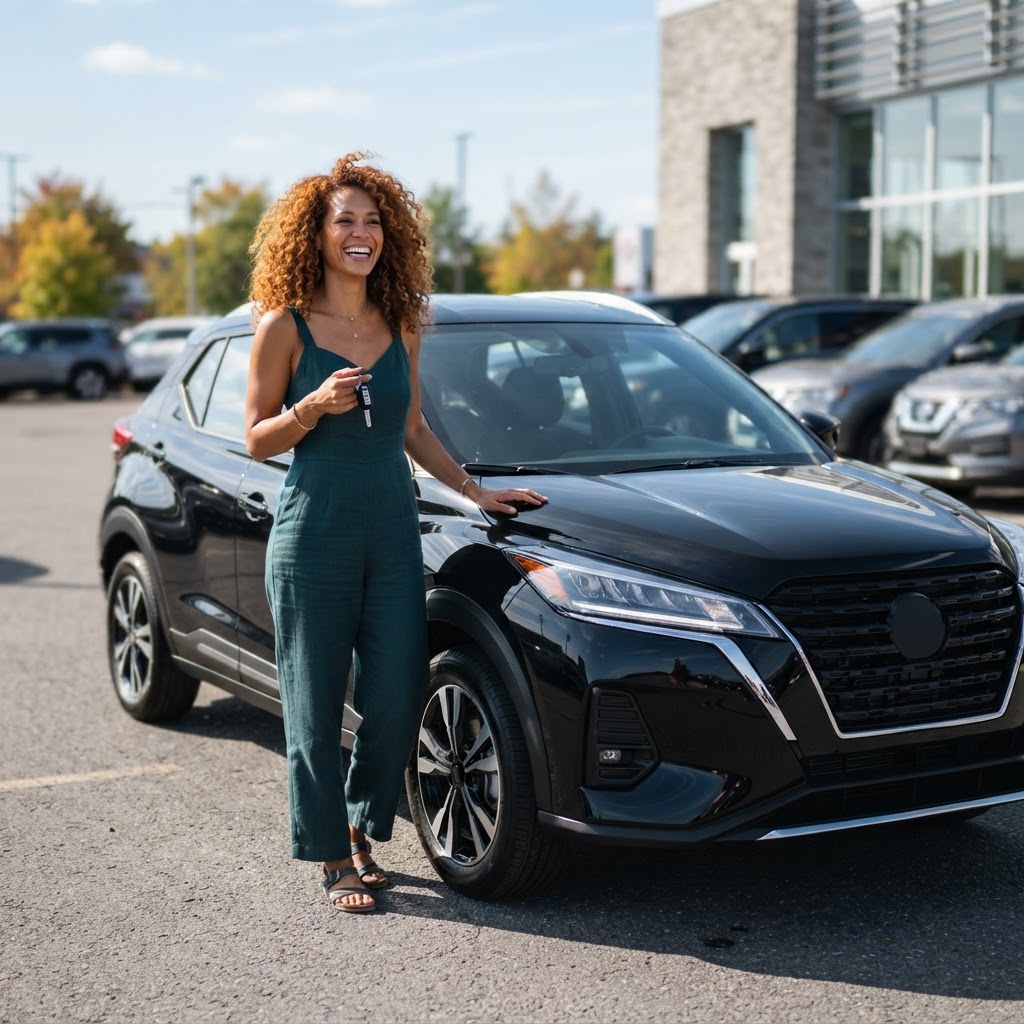
When she saw the vehicle in person—black, clean, and well-prepped—she felt a small shock. Not because it was extravagant, but because it represented so much more than just a car. It was proof that she was finally exiting the period where everything seemed closed off.
When she got the keys, she shed a few tears, which made her laugh afterward. She thought it was “intense for a car,” but deep down, it wasn’t just a car. It was the end of a long episode of rejection, embarrassment, and discouragement.
Leaving with more than just a vehicle
A few weeks later, Sandra said she was already sleeping better. She no longer had to ask her sister for rides when her old car refused to start. She arrived at work on time without the stress. And most importantly, she felt like she was regaining control.
What she often repeats is that she didn't experience a miracle. She experienced human support. Her credit file remained fragile. The rate reflected that reality. But someone took the time to look past the 538 score and saw a woman who had started paying her obligations seriously again.
Today, she sees her financing as a step in her reconstruction, not an extra burden. She makes her payments on time, watches her budget, and is proud to know that every month counts a little toward rebuilding her credit.
If you recognize yourself in her story—bankruptcy, consumer proposal, rejections elsewhere, feeling like everything is blocked—Sandra would say this: don’t wait until you have a perfect file to ask for help. Sometimes, all it takes is the right team to get things moving again. You can start your application here: /demande.
And if you currently feel ashamed, scared, or like you’ve “gone too far,” her message would be simple: your file does not define you forever. There are times when life gets rough, but there are also detours that you can correct one step at a time. Sometimes, the first real victory is simply starting to believe that you deserve a second chance.