When Julie no longer believed it was possible
Julie could no longer talk about cars without feeling a knot in her stomach. At 34, a mother to an 8-year-old boy, she had been working for a little over two years as an administrative assistant at a private clinic in Lévis, earning about $48,000 per year. On paper, her situation seemed stable again. In real life, it was more fragile.
Three years earlier, after a difficult separation and several months of juggling maxed-out credit cards, a late personal loan, and missed payments, Julie had to file a consumer proposal. Her credit score hovered around 562 when she contacted us. She still felt like she was carrying a label: "difficult file."
The hardest part for her wasn't just the credit. It was having already been rejected twice elsewhere. The first time was at a large dealership where they told her they would call her back, but never did. The second time was with a lender who demanded a down payment that was far too high for her. At that time, Julie was still driving an old 2011 compact that cost more in repairs than she wanted to admit. When the transmission started slipping, she felt like everything was falling on her shoulders at once.
The first call: a lot of embarrassment, a little hope
When she filled out her application at Prêt Auto Québec, Julie was honest with us: she was almost expecting another refusal. She had set aside $2,500 for a down payment, no more. She feared it was insufficient. She was also afraid of being judged because of her recent consumer proposal.
What our team explained to her right from the start was that the 2nd chance program exists precisely for situations like hers. Not to promise miracles, but to look at the entire file: stable employment, income, repayment capacity, and how she had started to regain discipline. We asked for her last two pay stubs, recent bank statements, driver's license, proof of address, and the details of her proposal. Nothing complicated, but enough to build a truly solid case.
Julie told us later that this was the moment she felt reassured. For the first time in a long time, she felt that people weren't just looking at her score.
The vehicle that restored her confidence
When we talked to her about her needs, she mostly wanted something reliable, economical, and recent enough to avoid unpleasant surprises. No luxury. Just peace of mind. The model that kept coming up in the conversation was the 2027 Nissan Kicks KICKS SV.
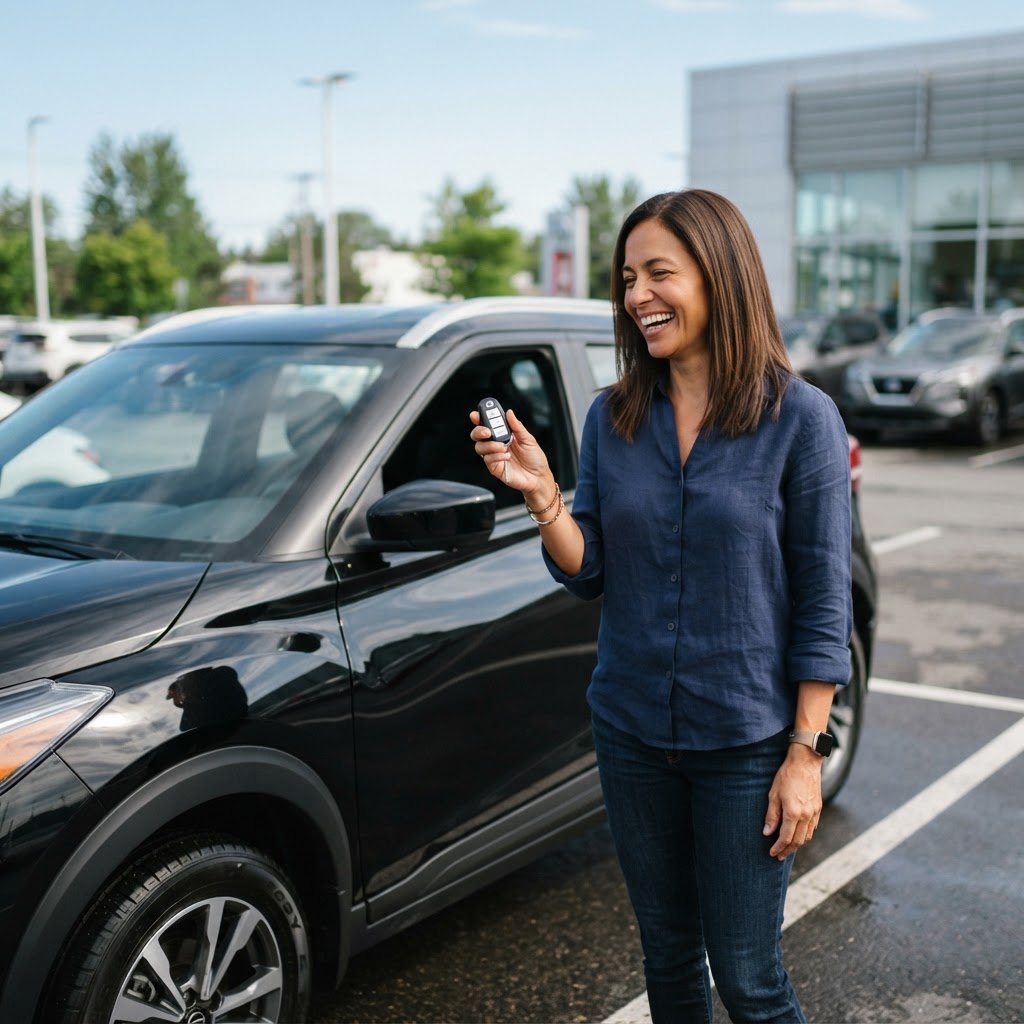
She liked it for the higher driving position, reasonable fuel consumption, and enough space for groceries, her son's school bag, and everyday life. When she saw it in person, in Black, she smiled, though she tried not to show it too much. She was still trying not to get too attached, for fear of being disappointed.
The 24 to 48-hour wait that felt endless
The financing package took a little less than two days. Technically, it was within the normal 24 to 48-hour window. To Julie, it felt much longer. She checked her phone between calls at work, and again in the evening after putting her son to bed.
In the end, the approval came through with realistic conditions. With her $2,500 down payment, she secured financing over 72 months at 11.99%. Her payment was approximately $298 bi-weekly. It wasn't a prime rate, and no one tried to make her believe otherwise. But for a client rebuilding after being rejected elsewhere, it was a real lifeline.
When we explained the numbers, Julie took a few minutes before responding. She wanted to be sure she wasn't putting herself in a tight spot again. After her fixed expenses—rent, occasional daycare, phone, insurance—she had a reasonable margin left. That's when she said yes, but with emotion. Not the spectacular excitement you see in commercials, but a long-held breath finally being released.
Signing day
On the day of signing, Julie arrived with her folder of documents as if she were taking an exam. She double-checked everything. She asked questions about payments, the possibility of refinancing later if her credit improved, and the impact of on-time payments on her file. Honestly, that was a good thing. A client rebuilding their credit is better off understanding everything.
When she signed, her hands were still shaking a little. Then came that very simple moment we see often, but which never becomes mundane: the keys being placed in her hand.
She called her mother from the parking lot before even leaving. Not to announce, "I bought a new car," but to say, "They gave me a chance."
More than a car, a concrete fresh start
A few weeks later, Julie wrote to us saying that, for the first time in a long time, she felt like she was moving forward instead of fixing the damage of the past. Her payment was going through easily. She was driving without fearing the next breakdown. And most importantly, she knew that every on-time payment was helping to rebuild her file.
That is exactly the spirit in which we work at Prêt Auto Québec. The 2nd chance program doesn't erase what happened. Instead, it allows for a fresh start on healthier ground, with an adapted vehicle and financing that the person can truly afford.
If you recognize yourself a little in Julie's story, know that a refusal elsewhere doesn't always mean "no" everywhere. You can apply here: /demande.
And if you currently feel ashamed of your credit, take a breath. Your file might tell the story of a difficult period, but it does not define your worth. Sometimes, all it takes is one right decision, at the right moment, to start believing in what comes next.