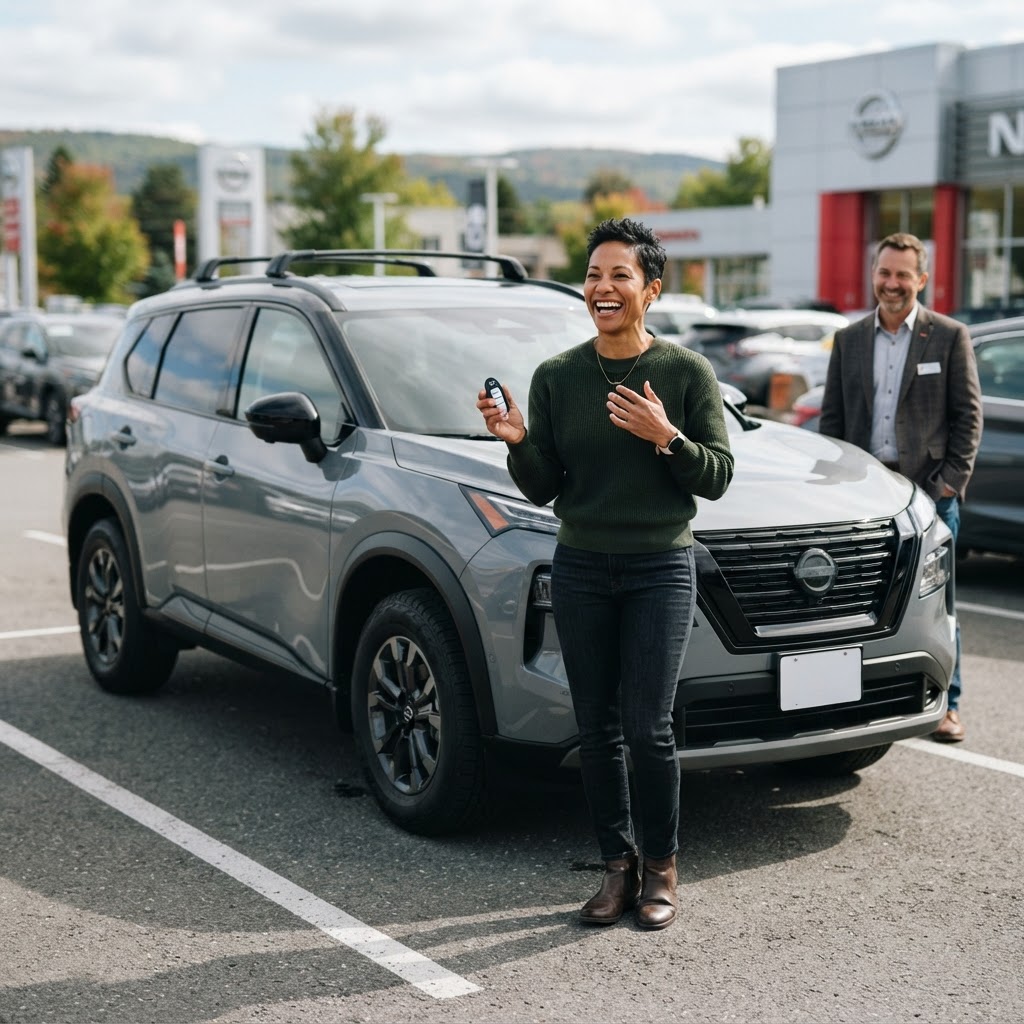
When Brigitte thought no one would ever say yes again
Brigitte wasn't the type to ask for help easily. At 42, she had been working for just over three years as an administrative assistant at a transportation company in Lévis, earning around $46,000 annually. She was also a single mother raising her 14-year-old son every other week, so every expense counted. On paper, her situation had begun to stabilize. In reality, she was still carrying the weight of some difficult years.
Two years earlier, after a complicated separation and a period on medical leave, she had filed a consumer proposal. Before that, several late payments had piled up, a credit card was nearly maxed out, and she was struggling to keep up with a personal loan. Her credit score hovered around 578. Not catastrophic forever, but enough to have doors slammed in her face quickly.
When her old SUV began costing more in repairs than in monthly payments, she tried shopping on her own. Two applications, two rejections. Once, she was even told that it would be better to wait “another year or two.” That was the moment, she said later, where she truly lost hope. She felt reduced to a number, as if the efforts she had made over the last few months didn't count.
A hesitant request... then a first real sense of relief
A colleague told her about the second-chance program at Prêt Auto Québec. Brigitte was hesitant. She expected to be judged or promised something impossible. Finally, one Tuesday evening, she filled out an online application at /demande, telling herself she had nothing to lose.
The next morning, an advisor called her back. Not to sell her a dream. Just to understand. Her job, her income, her consumer proposal, her current payments, and her actual budget. Brigitte was surprised by the tone. No pressure, no rehearsed script. They explained frankly that with a file like hers, it was necessary to build a solid application and demonstrate recent stability.
She was asked for her last two pay stubs, proof of employment, a bank statement, her driver’s license, and documents related to her consumer proposal. Nothing extraordinary, but enough to reassure the lender. She sent everything the same day, nervous and convinced that silence would follow.
Instead, she received a call about 24 hours later saying her file was moving forward well. Not yet signed, not yet final, but “it looks promising.” Just that sentence lifted a huge weight off her shoulders.
The vehicle she wanted without believing it was for her
Brigitte was looking for something reliable, spacious enough for winter, soccer practice, and weekends at her sister’s cottage. When she was shown the 2026 Nissan Rogue ROGUE ROCK CREEK, she laughed at first, saying it was “a bit too nice for her situation.”
And yet, it was exactly the kind of vehicle that met her needs. A reassuring driving position, practical cargo space, and a drivetrain well-suited to her daily life. The one she finally chose was grey, understated, elegant, not flashy—a detail she loved.
The real numbers behind her approval
Her approval came through in a little less than 48 hours. It wasn't perfect financing, and no one tried to make her believe otherwise. It was a real second-chance solution, realistic and structured to help her get back on track.
Brigitte was approved with a $2,500 down payment. Her interest rate was 12.49%, which, in the context of damaged credit and a recent consumer proposal, remained fair. An 84-month term was chosen to keep the payments within her budget. Her monthly installment amounted to approximately $318 every two weeks.
When the advisor presented the numbers to her, Brigitte was silent for a long time. Not because she was disappointed. Because she was doing the math in her head, comparing it to the unpredictable repairs of her old vehicle, the stressful days, and the rejections. For the first time in a long time, she saw that something was possible.
The day of signing, then the day of the keys
She arrived at the dealership still wary. Many second-chance clients arrive like that, feeling like one small detail will cause everything to fall apart at the last minute. They reviewed the documents with her, reread the contract, explained the conditions, and answered her questions about the payments and how this new loan could help her rebuild her credit score if everything remained paid on time.
Brigitte signed with slightly shaking hands. She admitted it with a laugh afterward. When everything was confirmed and she was handed the keys, she sat for a few seconds in her Rogue without starting the engine. Just to breathe.
She wasn't quite crying, but almost.
More than a vehicle, a fresh start
A few weeks later, she called back to say thank you. Not just for the financing, but for how she had been treated. With respect. With honesty. Without discomfort regarding her past.
Today, Brigitte sees this vehicle as much more than just a means of transport. It is concrete proof that a bad financial chapter does not define an entire life. Her credit didn't heal overnight. But every on-time payment gives her a little more confidence, a little more breathing room, and a little more pride.
At Prêt Auto Québec, this is exactly the spirit of the second-chance program: to help people who have stumbled but are ready to make a serious fresh start with human guidance and realistic numbers.
If you recognize yourself in Brigitte’s story, don’t wait until your file is “perfect” to take the first step. Sometimes all it takes is the right support to turn a rejection into a concrete plan. You can submit your application here: /demande.
And above all, if you have ever felt like your financial past would follow you forever, remember this: you can fall, get back up, and start over with dignity. Brigitte is proof of it.